SSM Registration No. 202603233841 (003885488-H)

Proprietary trading · Quantitative research · Kuala Lumpur

Research-led decisions.
Risk-defined execution.

QuantaEdge is a Malaysian proprietary trading and research company focused on systematic decision-making across futures, options, warrants and liquid fixed-income instruments.

We combine quantitative testing, macroeconomic context, market microstructure and portfolio-level risk analysis to develop repeatable frameworks for capital allocation.

Current AUMRM100,000.00Internally reported
Research pillars04Quant · Macro · Risk · Microstructure
01

Introduction to the team

Two complementary disciplines.
One risk-first process.

QuantaEdge is led by two founders whose responsibilities connect portfolio construction, trading execution and quantitative research.

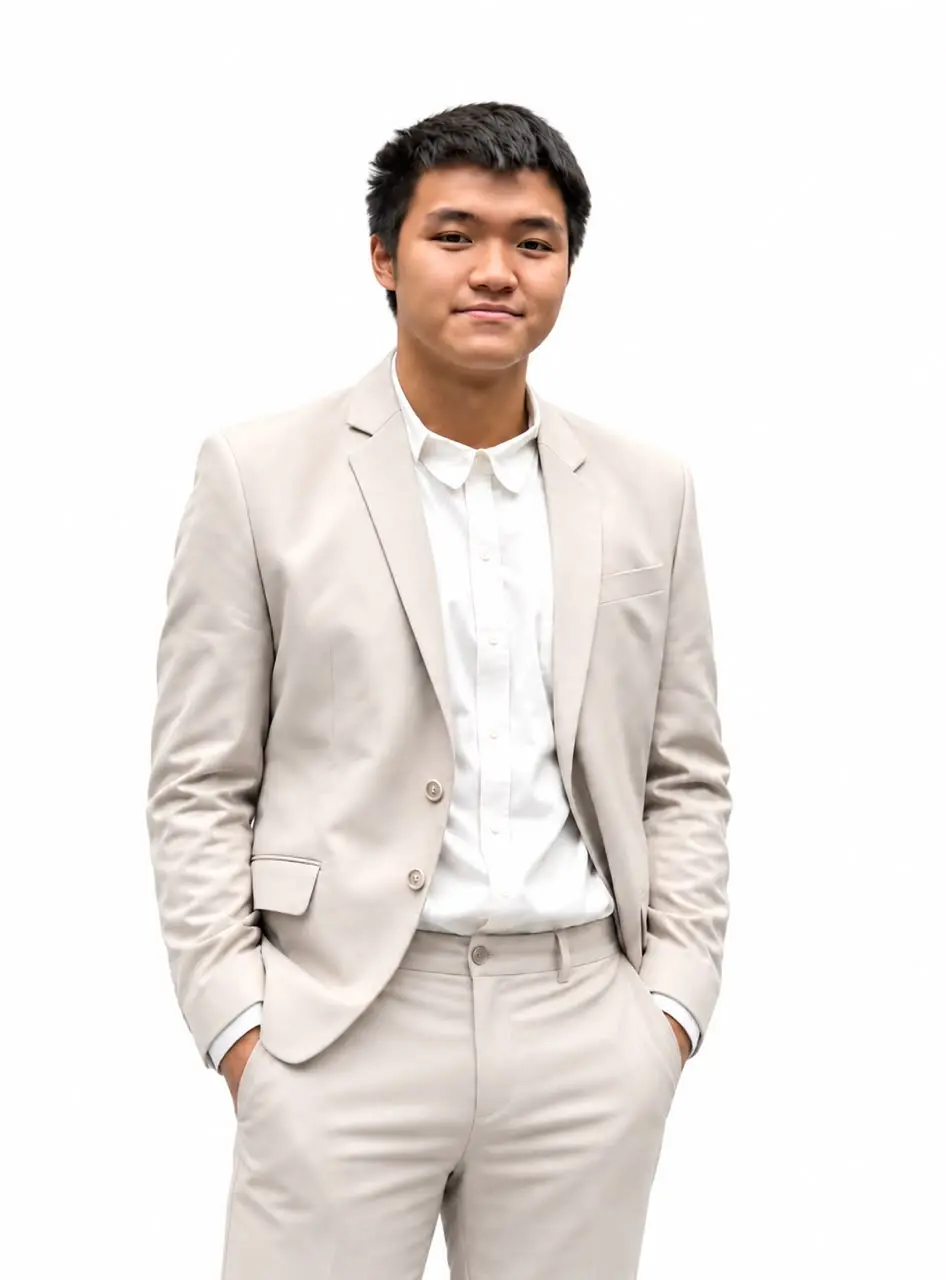
Piong Hong Yun, Founder and Head of Proprietary Trading
Founder 01

Piong Hong Yun

Founder / Head of Proprietary Trading

Leads portfolio management, proprietary trading execution and risk analysis across the firm's active strategies.

  • Portfolio construction and capital allocation
  • Position, drawdown and concentration risk
  • Cross-market trading oversight
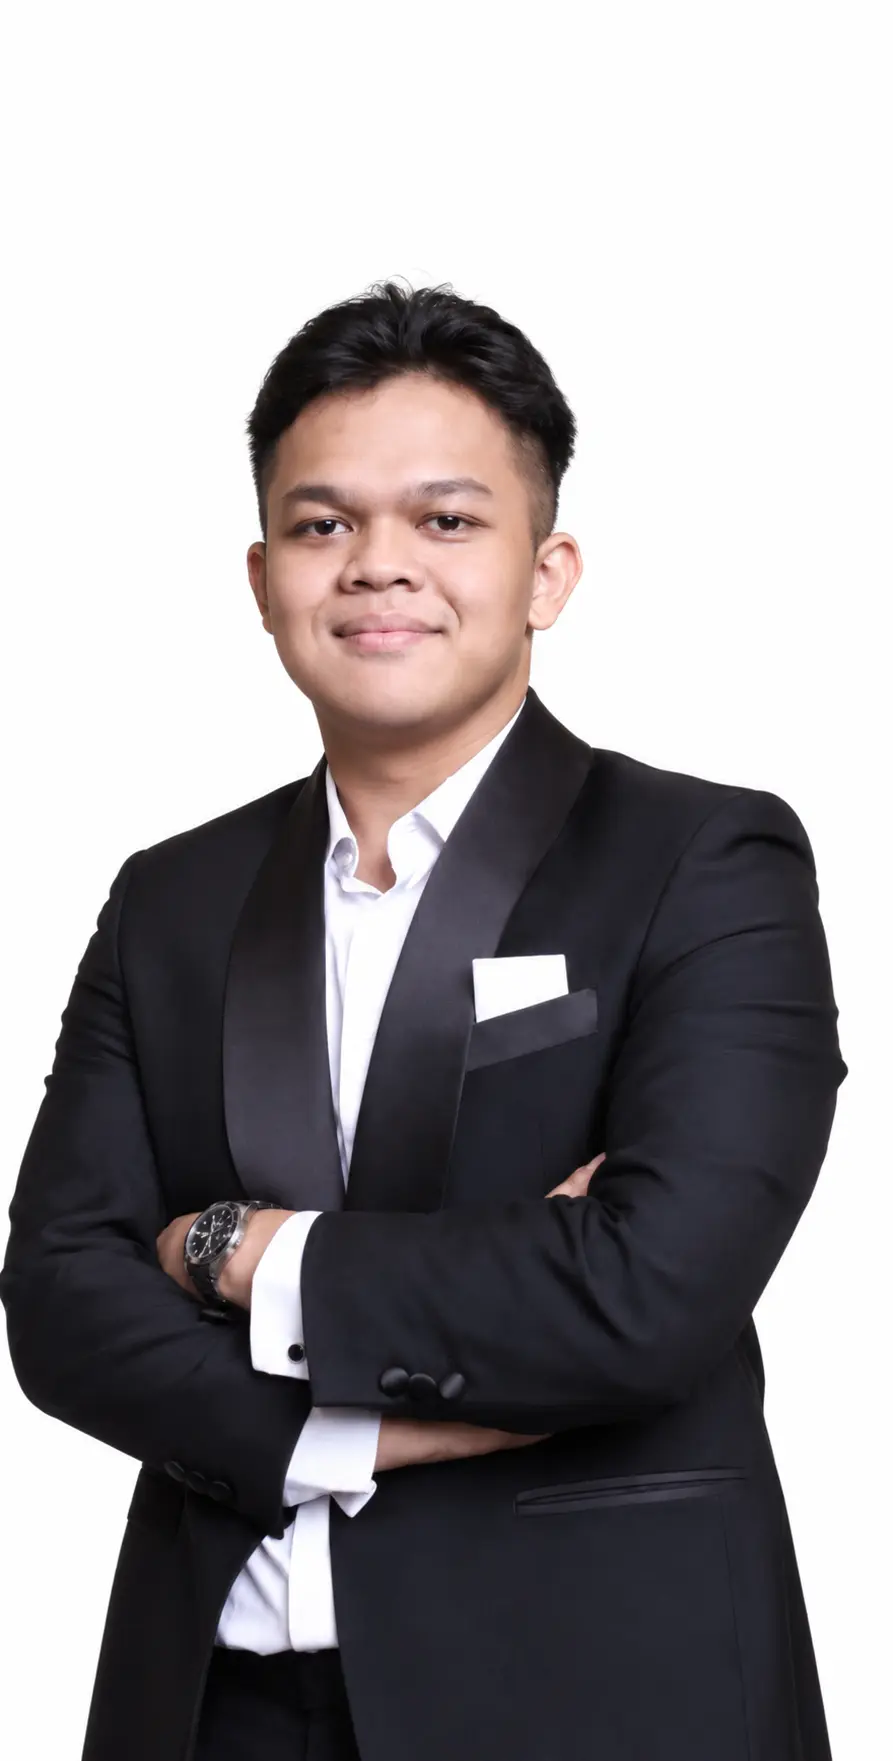
Denver Lim Le, Founder and Head of Quantitative Research
Founder 02

Denver Lim Le

Founder / Head of Quantitative Research

Leads quantitative research, model validation and portfolio diversification analysis across multiple market regimes.

  • Systematic strategy research and testing
  • Portfolio diversification and factor analysis
  • Market microstructure research
02

Our research reports

A transparent research library.

Publish market studies, quantitative validation notes and risk analyses in a consistent PDF format. Every report should state its methodology, data period, assumptions and limitations.

Published research

Download QuantaEdge research notes and market studies.

Public library

Loading published research…

03

Our location

Kuala Lumpur,
Malaysia.

Unit 11-2-1, Block I
Jalan 3/101C, Cheras Business Centre
56100 Cheras, Kuala Lumpur
Open in Google Maps ↗
04

Our portfolio management engine

Multiple return drivers.
One portfolio view.

Strategies are evaluated as a portfolio rather than in isolation. Allocation should reflect correlation, liquidity, drawdown behaviour and changing market regimes.

01
⇄

Calendar Spread & Relative Value

Studies price relationships across contract months and related instruments while accounting for basis, liquidity and leg-execution risk.

Curve structure · Seasonality · Spread risk
02
↗

Trend Following

Uses systematic confirmation and risk-defined exits to participate in directional moves without assuming trends will persist.

Signal quality · Volatility · Position sizing
03
◉

Macro Event Driven

Frames policy, inflation, labour and liquidity events through scenario analysis instead of relying on a single-point forecast.

Rates · Inflation · Liquidity regimes
04
⌁

Market Microstructure

Analyses quote activity, price acceptance, positioning and volatility to improve market context and execution decisions.

Tick data · Options positioning · Execution
05

Capital and allocation

Current AUM
RM100,000.00

This allocation balances directional and relative-value strategies with a larger liquidity reserve. Figures are internally reported and should be read together with the risk statement below.

Current allocationAs at September 2026

30.00%US Futures / Local Futures

30.00%US Options / HSI Warrants

40.00%Fixed Income / MMF

Monthly performance reports

Published monthly updates and performance documents.

Public library

Loading published reports…

06

Events we have attended

Learning directly from the market.

We attend institutional market briefings and industry forums to strengthen our understanding of macro conditions, corporate perspectives, derivatives and market structure.

Loading event highlights…

07

Our one-year goal

Deepen the research bench.

Our operating target is to grow responsibly while adding specialists who strengthen coverage—not simply increasing trading volume.

Team objective01

10 specialists

A multidisciplinary team covering quantitative research, macro, execution, portfolio risk and operations.

Measured by capability, not headcount alone
08

Contact us

Start a professional
conversation.

For research collaboration, institutional enquiries or company information, contact the team through the channels below.